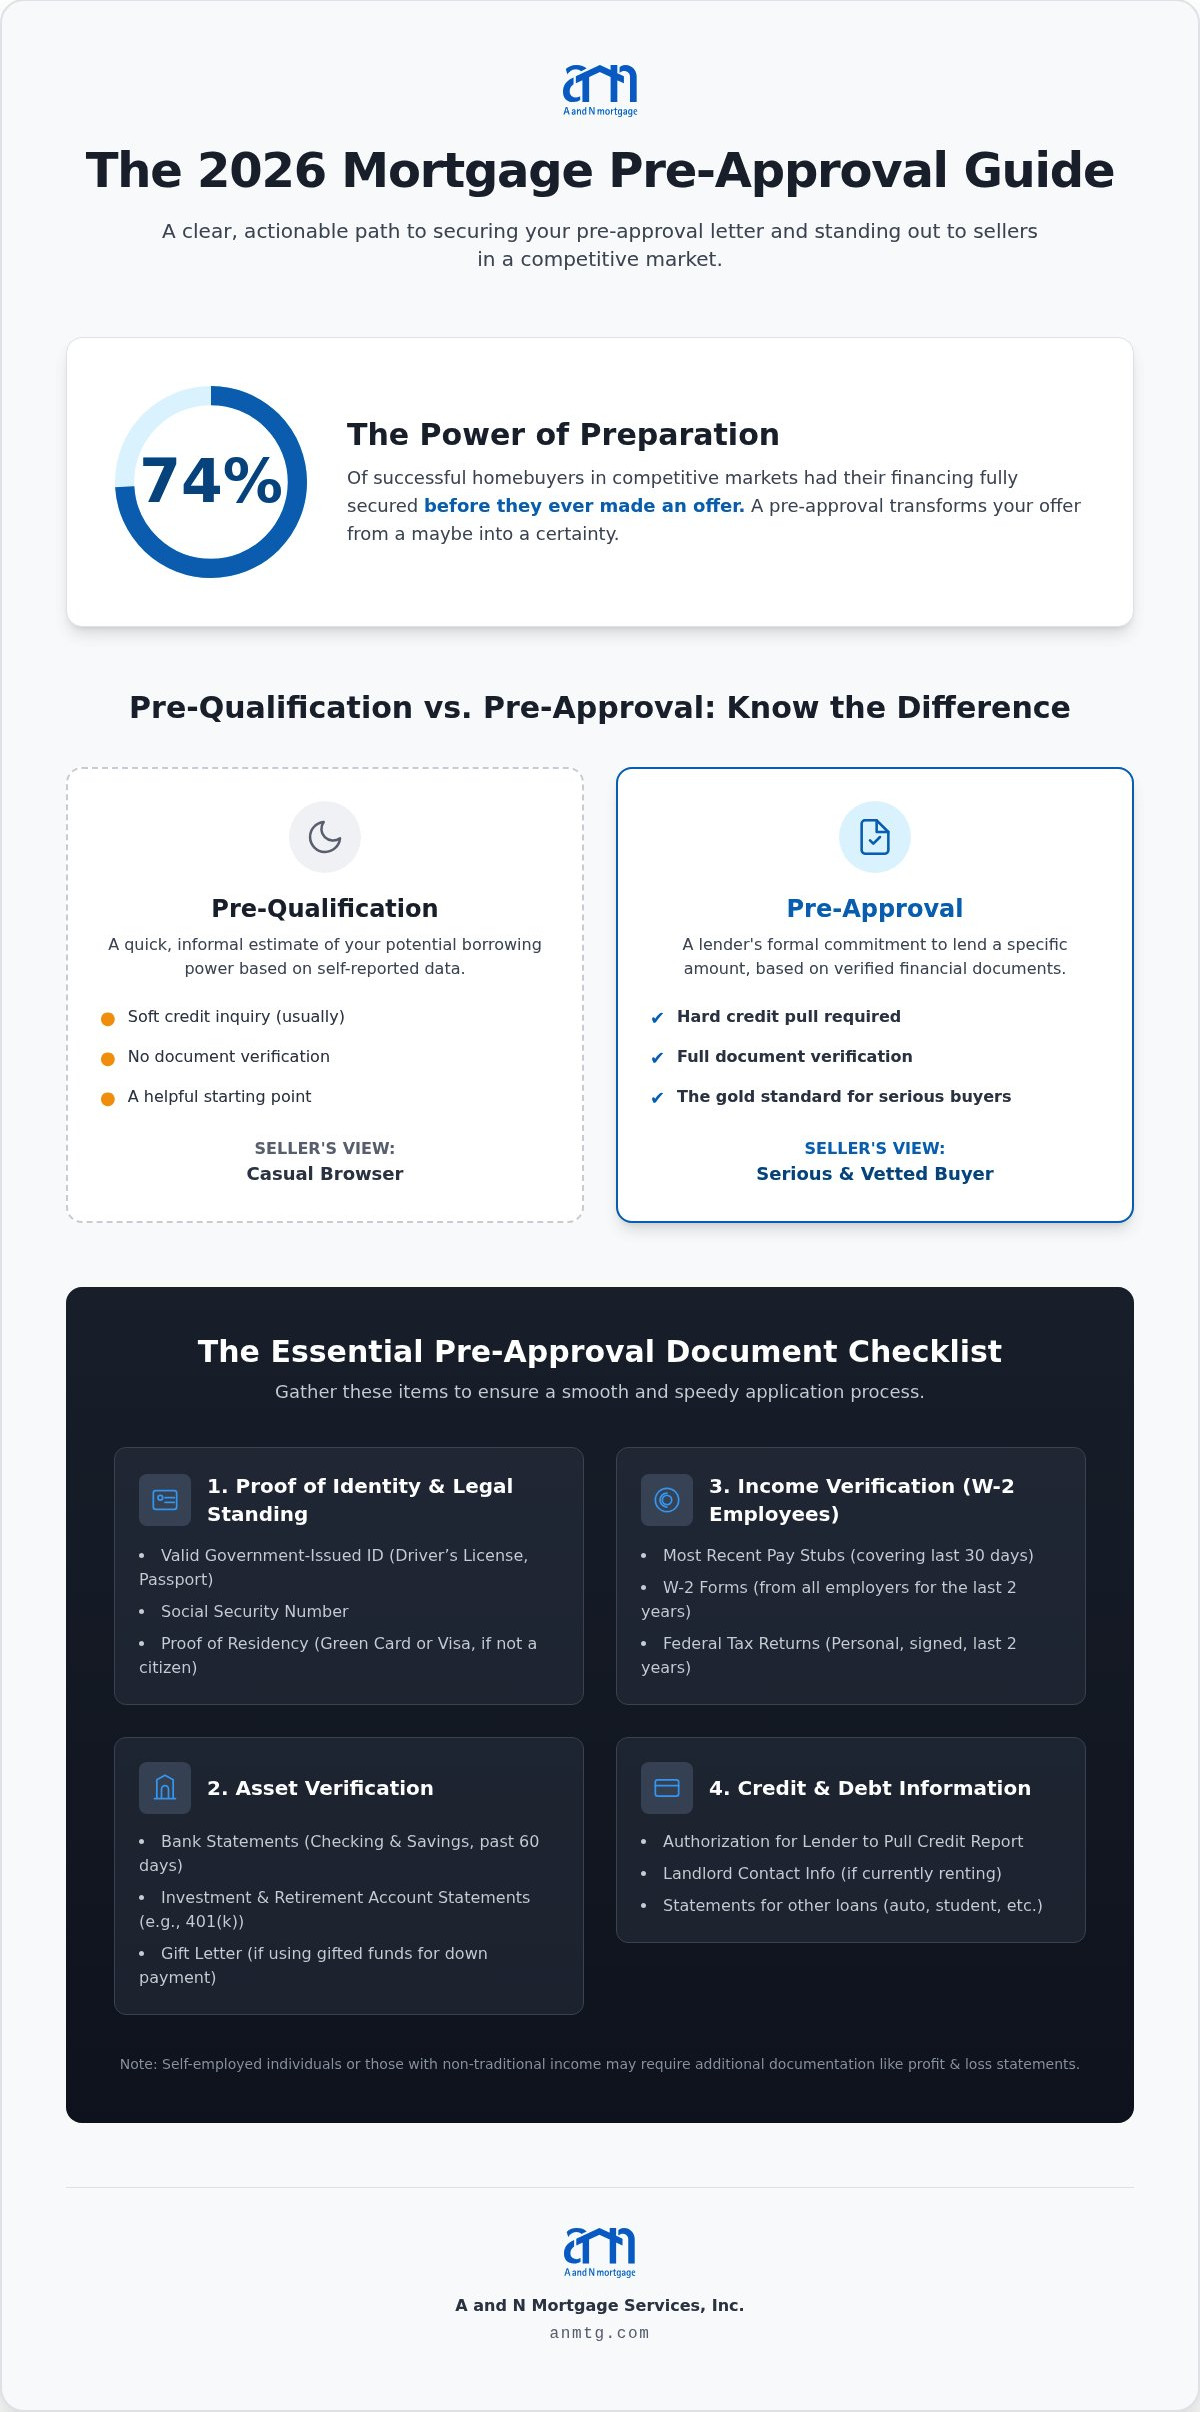
Did you know that 74% of successful homebuyers in competitive markets had their financing secured before they ever made an offer? It's a staggering figure that highlights why walking into a showing without a comprehensive mortgage pre-approval checklist is a risk you can't afford to take. We understand that gathering every bank statement and tax return feels like a mountain of paperwork, especially when you're worried about your credit score or debt-to-income ratio. You want to feel mortgage-ready rather than anxious about a potential rejection.
Our goal is to transform that anxiety into a sense of informed confidence. This guide provides a clear, actionable path to securing your pre-approval letter, ensuring you stand out to sellers and realtors alike. We'll explore the specific documentation required for 2026, clarify the often-confusing distinction between pre-qualification and pre-approval, and offer the seasoned guidance necessary to navigate your home-buying journey with total stability. By the time you finish reading, you'll have the tools to move from initial curiosity to a state of complete readiness.
In the fast-moving real estate environment of 2026, a mortgage pre-approval is much more than a simple document. It's a lender's formal commitment to provide you with a specific loan amount based on a rigorous verification of your financial history. By Understanding Mortgage Pre-Approval, you position yourself as a vetted buyer rather than a casual browser. This process provides a definitive answer to what you can actually afford, which prevents the heartbreak of falling in love with a home that sits outside your financial reach.
Think of it as a defensive shield for your home-buying journey. While interest rates for 30-year fixed mortgages have stabilized in the mid-6% range as of late 2026, the market remains competitive. Having your numbers verified early allows you to move with the speed and fluidity necessary to secure a property before other buyers can react. It transforms your offer from a "maybe" into a "certainty" in the eyes of a seller.
Many first-time buyers confuse these two terms, but the distinction is vital for your success. A pre-qualification is merely a soft estimate based on information you provide without any third-party verification. It's a helpful starting point, but it doesn't carry weight with sellers. In contrast, a pre-approval requires a hard credit pull and a thorough review of your mortgage pre-approval checklist documents. This deep dive gives the lender the confidence to back your offer by verifying:
Ultimately, a pre-approval is the gold standard for serious buyers who want to demonstrate their financial readiness and professional approach.
In markets like Chicago, realtors often won't show homes to anyone who hasn't secured a pre-approval letter. They want to know you're a qualified candidate who won't face a rejection late in the process due to a hidden debt-to-income issue or credit snag. When you enter a bidding war, your pre-approval letter serves as your ticket to entry. It signals to the seller that your financing is stable and that the path to closing will be efficient.
By completing your mortgage pre-approval checklist ahead of time, you also shave weeks off the eventual closing timeline. This speed makes your offer significantly more attractive to sellers who are eager to move forward without delays. It shows you have a professional in your corner who is ready to facilitate a seamless transaction.
Organizing your financial life into a structured mortgage pre-approval checklist is the single most effective way to reduce stress during the home-buying process. Lenders require a high level of specificity to verify your ability to repay a loan; this means you should prepare to provide documents that are "fresh," typically dated within the last 30 to 60 days. Whether you prefer digital folders on a secure drive or physical binders, keeping these records accessible ensures a fluid experience when your loan officer requests updates. Having everything ready at the outset allows you to move at the speed of the 2026 market.
Your lender must confirm your identity to comply with federal regulations. This foundational step requires a valid, government-issued ID, such as a driver's license or a current passport. You'll also need to provide your Social Security Number to allow for the mandatory credit and background checks. If you aren't a U.S. citizen, be prepared to include proof of residency, such as a Green Card or a valid Visa, to establish your legal standing for a residential loan.
Verifying your earnings is where the process becomes highly detailed. According to official pre-approval guidance, lenders need to see a consistent and stable history of income. You'll need your most recent 30 days of pay stubs that clearly display your year-to-date earnings. Additionally, gather your W-2 forms from the last two years to show income longevity. It's also helpful to have the direct contact information for your HR department, as most lenders will perform a digital verification of employment shortly before finalizing your pre-approval.
This portion of your mortgage pre-approval checklist is often the most scrutinized because lenders look for "seasoned" funds to cover your down payment and closing costs. You must provide the last 60 days of statements for all checking and savings accounts. A common mistake is omitting blank pages; you must include every single page of a statement, even if it's completely blank, to prove the document hasn't been altered. Don't forget quarterly statements for retirement accounts like a 401k or IRA, as well as brokerage statements. If you're receiving help from family, you'll need a signed gift letter and documentation showing the transfer of those funds. While the lender will pull your credit report to see your debts, it's wise to have recent statements for any student loans or car payments ready if questions arise about your monthly obligations.
While gathering these documents might feel overwhelming, having a trusted mortgage partner in your corner makes the process significantly more manageable and efficient.
Not every homebuyer fits into a standard financial box. If you're a business owner, a medical professional, or a veteran, your mortgage pre-approval checklist will naturally look different than that of a traditional W-2 employee. A and N Mortgage acts as a Seasoned Guide for these unique paths, offering specialized loan programs that account for non-traditional income streams or high debt-to-income ratios. We prioritize a fluid process that respects the complexity of your situation without sacrificing the speed or efficiency required in a competitive market.
Entrepreneurs often encounter extra scrutiny during the verification phase. Because your income can fluctuate based on business cycles, lenders need a deeper look at the long-term stability of your enterprise. You'll need to provide two years of both personal and business federal tax returns, ensuring every schedule and attachment is included. Beyond tax filings, a year-to-date Profit and Loss (P&L) statement and a current balance sheet are mandatory to show your business's current performance. If you have partners or own multiple entities, be prepared to provide K-1s for each ownership stake. This thoroughness allows us to build a strong, verified narrative of your financial health.
Medical professionals often start their careers with high student loan debt that doesn't reflect their true earning power. Our Doctor Loan options address this gap specifically. Instead of waiting for months of pay stubs, we can often utilize a signed employment contract that shows your future start date and guaranteed salary. We also provide specialized handling of student loan debt in DTI calculations; we often use modified calculations if your loans are in deferment or forbearance. This versatility ensures that residents and established physicians alike can secure a home that matches their professional standing without being penalized for their education.
Serving those who served requires a deep understanding of specific federal requirements. Your primary document is the Certificate of Eligibility (COE), which confirms your entitlement to VA benefits. You'll also need to provide your Statement of Service or DD214 to verify your discharge status and eligibility. If you receive disability income or other military-specific allowances, documenting these accurately is vital for your qualifying income. We treat these applications with a high level of advocacy, ensuring our veterans receive the benefits they've earned through their service.
If you're planning to build a custom home or renovate a fixer-upper, the paperwork expands to include the project itself. You'll need detailed construction plans, a signed contract with a licensed builder, and a comprehensive line-item budget. These documents ensure the Construction Loan or Renovation Loan covers the full scope of your project, providing a stable foundation for your future home.
Before you begin checking off items on your mortgage pre-approval checklist, you should conduct a rigorous self-audit of your current financial health. This preparation phase acts as a defensive shield, ensuring that when a lender reviews your file, they see a profile characterized by stability and reliability. Taking a few months to "polish" your numbers can be the difference between a standard offer and a premier rate that saves you significant capital over the life of your loan.
Chicago residents face unique challenges, particularly regarding local property taxes which are often higher than the national average. These taxes are factored directly into your monthly housing payment, which means they have a direct impact on your debt-to-income (DTI) ratio. By understanding these local nuances early, you can adjust your expectations and your budget accordingly, avoiding any surprises during the formal application process. It's about moving from a state of curiosity to a state of complete readiness.
Lenders evaluate two specific DTI figures: your front-end ratio, which covers housing costs, and your back-end ratio, which includes all monthly debt obligations like car loans or student debt. If your ratios are tight, consider paying down small revolving balances first. Even a minor $50 monthly credit card payment can reduce your borrowing power more than you might realize. To help offset the upfront costs of buying and keep your cash reserves high for debt reduction, you might explore down payment assistance Illinois programs that are designed to support local buyers in achieving homeownership.
Your credit score is the primary lever for your interest rate. While you're preparing your mortgage pre-approval checklist, avoid opening any new credit lines or making large financed purchases like a new vehicle. These actions can cause your score to dip or create new monthly obligations that skew your DTI. Instead, focus on disputing any errors on your credit report well before the lender performs a hard pull. A simple correction that leads to a 20-point boost can save you thousands of dollars in interest charges over a 30-year mortgage term.
Taking these proactive steps ensures you enter the market with a level of informed confidence that sellers find attractive. It's about being more than just ready; it's about being the most qualified buyer in the room. By organizing your finances now, you ensure the path ahead is fluid and free of unnecessary hurdles.
Connect with a trusted ally to review your financial readiness
Once you have completed your mortgage pre-approval checklist, the transition from document gathering to active home searching should be a moment of excitement, not stress. At A and N Mortgage, we believe that the right partnership transforms a complex financial transaction into a clear, manageable journey. While national "big box" lenders often rely on impersonal algorithms and distant call centers, our Chicago-based team offers the advocacy and personalized care required to navigate the specific demands of the 2026 market.
We understand that you aren't just looking for a loan; you're looking for a home. This distinction is what drives our commitment to providing a fluid, transparent process from your initial application through to the day you receive your keys. By choosing a local partner, you gain access to experts who understand the nuances of Illinois property taxes and the local real estate climate, ensuring your pre-approval is both accurate and respected by sellers.
With over 24 years of local expertise, A and N Mortgage has established itself as a "Seasoned Guide" for thousands of homeowners. Led by Neena Vlamis, our team has been navigating the complexities of residential lending since 1998, providing a level of stability that only comes with decades of experience. We pride ourselves on being a "Trusted Ally," acting as a defensive shield for our clients by ensuring every detail of their application is optimized before it reaches an underwriter.
Our versatility allows us to offer a wide breadth of products, including Conventional, FHA, VA, and Jumbo Loans, as well as specialized solutions like Construction and Renovation Loans. This variety ensures that every borrower, regardless of their unique financial path, finds a solution tailored to their specific needs. By bridging the gap between a long-standing history of service and a modern, tech-forward approach, we provide the speed and fluidity you need to secure your dream home in a fast-paced environment.
The most effective way to maintain your momentum is to act while your financial data is fresh. We recommend spending the next 24 hours organizing a secure digital folder based on our mortgage pre-approval checklist. Gathering your pay stubs, tax returns, and bank statements now ensures that when you reach out to our team, we can move with immediate efficiency. Having these items organized is the best way to demonstrate your readiness to realtors and sellers alike.
Our digital application process is designed to be low-friction and intuitive, allowing you to upload documents securely and track your progress in real-time. This blend of high-tech tools and high-touch personal service means you're never left wondering about your status. You deserve a partner who is as invested in your success as you are. When you're ready to move from initial curiosity to a state of informed confidence, we're ready to help you take that first step.
Reach out to a knowledgeable professional at A and N Mortgage today to begin your path toward homeownership with a partner you can trust.
Success in the 2026 housing market depends on your ability to move with both speed and certainty. By completing your mortgage pre-approval checklist before you visit your first open house, you transform from a curious observer into a fully vetted, competitive buyer. You now have the tools to audit your own financial health, manage your debt-to-income ratio, and gather the specific documentation required for a fluid application process.
A and N Mortgage stands ready to serve as your steady partner throughout this journey. With over 24 years of mortgage expertise and a deep understanding of the local Chicago market, we offer a wide range of loan programs tailored to your life. We bridge the gap between established stability and modern, tech-forward service to ensure your path to homeownership remains clear and manageable.
Get Started on Your Reassuring Path to Homeownership with A and N Mortgage
Your dream home is within reach, and the right preparation makes all the difference. We look forward to helping you navigate this milestone with the advocacy and professional care you deserve.
Most pre-approvals are valid for 60 to 90 days. This timeframe allows you to shop the Chicago market with a current snapshot of your financial health. If your search extends beyond this period, your lender will simply need updated documents from your mortgage pre-approval checklist, such as recent pay stubs or bank statements. This ensures your verified data remains accurate as interest rates or market conditions shift during your home-buying journey.
A mortgage pre-approval involves a hard credit inquiry, which typically results in a small, temporary dip of fewer than five points. This minor impact is a necessary step to verify your creditworthiness and secure the best possible rates. Most credit scoring models recognize when you're "rate shopping" for a home loan, so multiple inquiries within a short window usually count as a single event, protecting your overall financial standing while you explore options.
You can definitely get pre-approved after starting a new position, especially if you've remained in the same industry or have a signed employment contract. Lenders look for income stability rather than just tenure at a single company. If you've recently transitioned, be prepared to provide an offer letter or your first pay stub to confirm your new salary. This versatility allows career-driven individuals to move forward with their home-buying goals without unnecessary delays.
The baseline credit score required for a conventional loan pre-approval in 2026 is typically 620. While this is the minimum, higher scores often unlock more favorable interest rates and lower private mortgage insurance costs. If your score is currently below this threshold, our team can act as a seasoned guide to help you identify steps to strengthen your profile. Consistent on-time payments and reducing revolving debt are the most effective ways to boost your standing.
A denial isn't the end of your journey; it's a signal to adjust your financial strategy. Your lender will provide an adverse action notice explaining the specific reasons, such as a high debt-to-income ratio or insufficient documentation. We recommend reviewing your mortgage pre-approval checklist to see where gaps exist. Whether you need to pay down a car loan or correct a credit report error, we'll work as your trusted ally to create a path for a successful re-application.
You don't need a specific address to begin the pre-approval process. In fact, getting pre-approved first is the strategic choice because it defines your realistic budget and proves your buying power to Chicago realtors. The letter will state the maximum loan amount you're qualified for based on verified data. This allows you to fall in love with a home that fits your financial profile, ensuring your eventual offer is both stable and competitive.
No, a pre-approval is a conditional commitment, while a final loan commitment occurs only after a specific property passes inspection and appraisal. The pre-approval is your ticket to entry in the market, showing you've passed the initial verification of income and assets. The full commitment is the final stage of underwriting where the lender confirms the home's value and your continued financial stability. Both steps are essential milestones in a fluid path toward closing.
Welcome to a better mortgage experience! In just few minutes you can find out what you qualify for and explore multiple loan options and interest rates.
Complete our short and intuitive pre-approval interview to get started.