The costliest first-home mistakes often start with assumptions that haven’t been tested. If you’re wondering what to avoid when buying your first home, start with decisions that can affect your budget, financing, and confidence before you make an offer. This guide to first time home buyer mistakes to avoid helps you look beyond the listing price and an online mortgage estimate.
It’s understandable to focus on finding a home you love, especially when the buying process feels unfamiliar. Preparation can help you catch potential missteps early, from stretching your budget too far to overlooking recurring expenses or rushing through property due diligence.
Use this checklist to review the full cost of homeownership, compare financing options that fit your situation, and decide what to examine before committing to a property. You’ll also learn how to prepare for a mortgage conversation and where Chicago-area buyers may find local or state down payment assistance. Knowing what to ask and review can help you make decisions with greater confidence.
Buying your first home can feel like a race to make the right decision, but preparation gives you room to move thoughtfully. A checklist can help you identify common risks, although it can’t eliminate every surprise or guarantee a smooth purchase. One of the first time home buyer mistakes to avoid is acting on assumptions before checking your financial readiness and clarifying what matters most in a home. Early planning helps you identify questions before they turn into urgent decisions.
Browsing listings can show you what’s available, but it can’t tell you whether a home fits your needs or budget. Before touring, write down your priorities and sort them into essentials and flexible preferences. A workable commute, for example, may be essential, while a particular finish or extra room may be negotiable. Treat listing details and online estimates as starting points, not a personalized assessment.
Use your list to keep the search focused. You might organize it this way:
In Chicago, two homes with similar listing prices can still differ in ways that affect your routine and priorities. A written list makes it easier to compare properties against what matters to you, rather than letting a polished listing or memorable tour reshape your plans on the spot.
It’s tempting to put off financing conversations until you find a home you love. An early discussion with a mortgage professional can help you understand which financing paths may fit your situation and set a more realistic search range. That context can keep you from becoming attached to a property before you’ve considered how its price and potential payment fit your plans.
Online calculators offer a useful first estimate, but they can’t account for every detail of your finances or loan options. The CFPB’s guide to buying a home can help you prepare questions. Personalized guidance can connect those concepts to your circumstances. You don’t need every answer before browsing, but it’s wise to know what you’re working toward before making an offer. When you’re ready to explore pre-approval, organize your financial information and questions in advance. Our 2026 mortgage pre-approval checklist walks through what to gather.
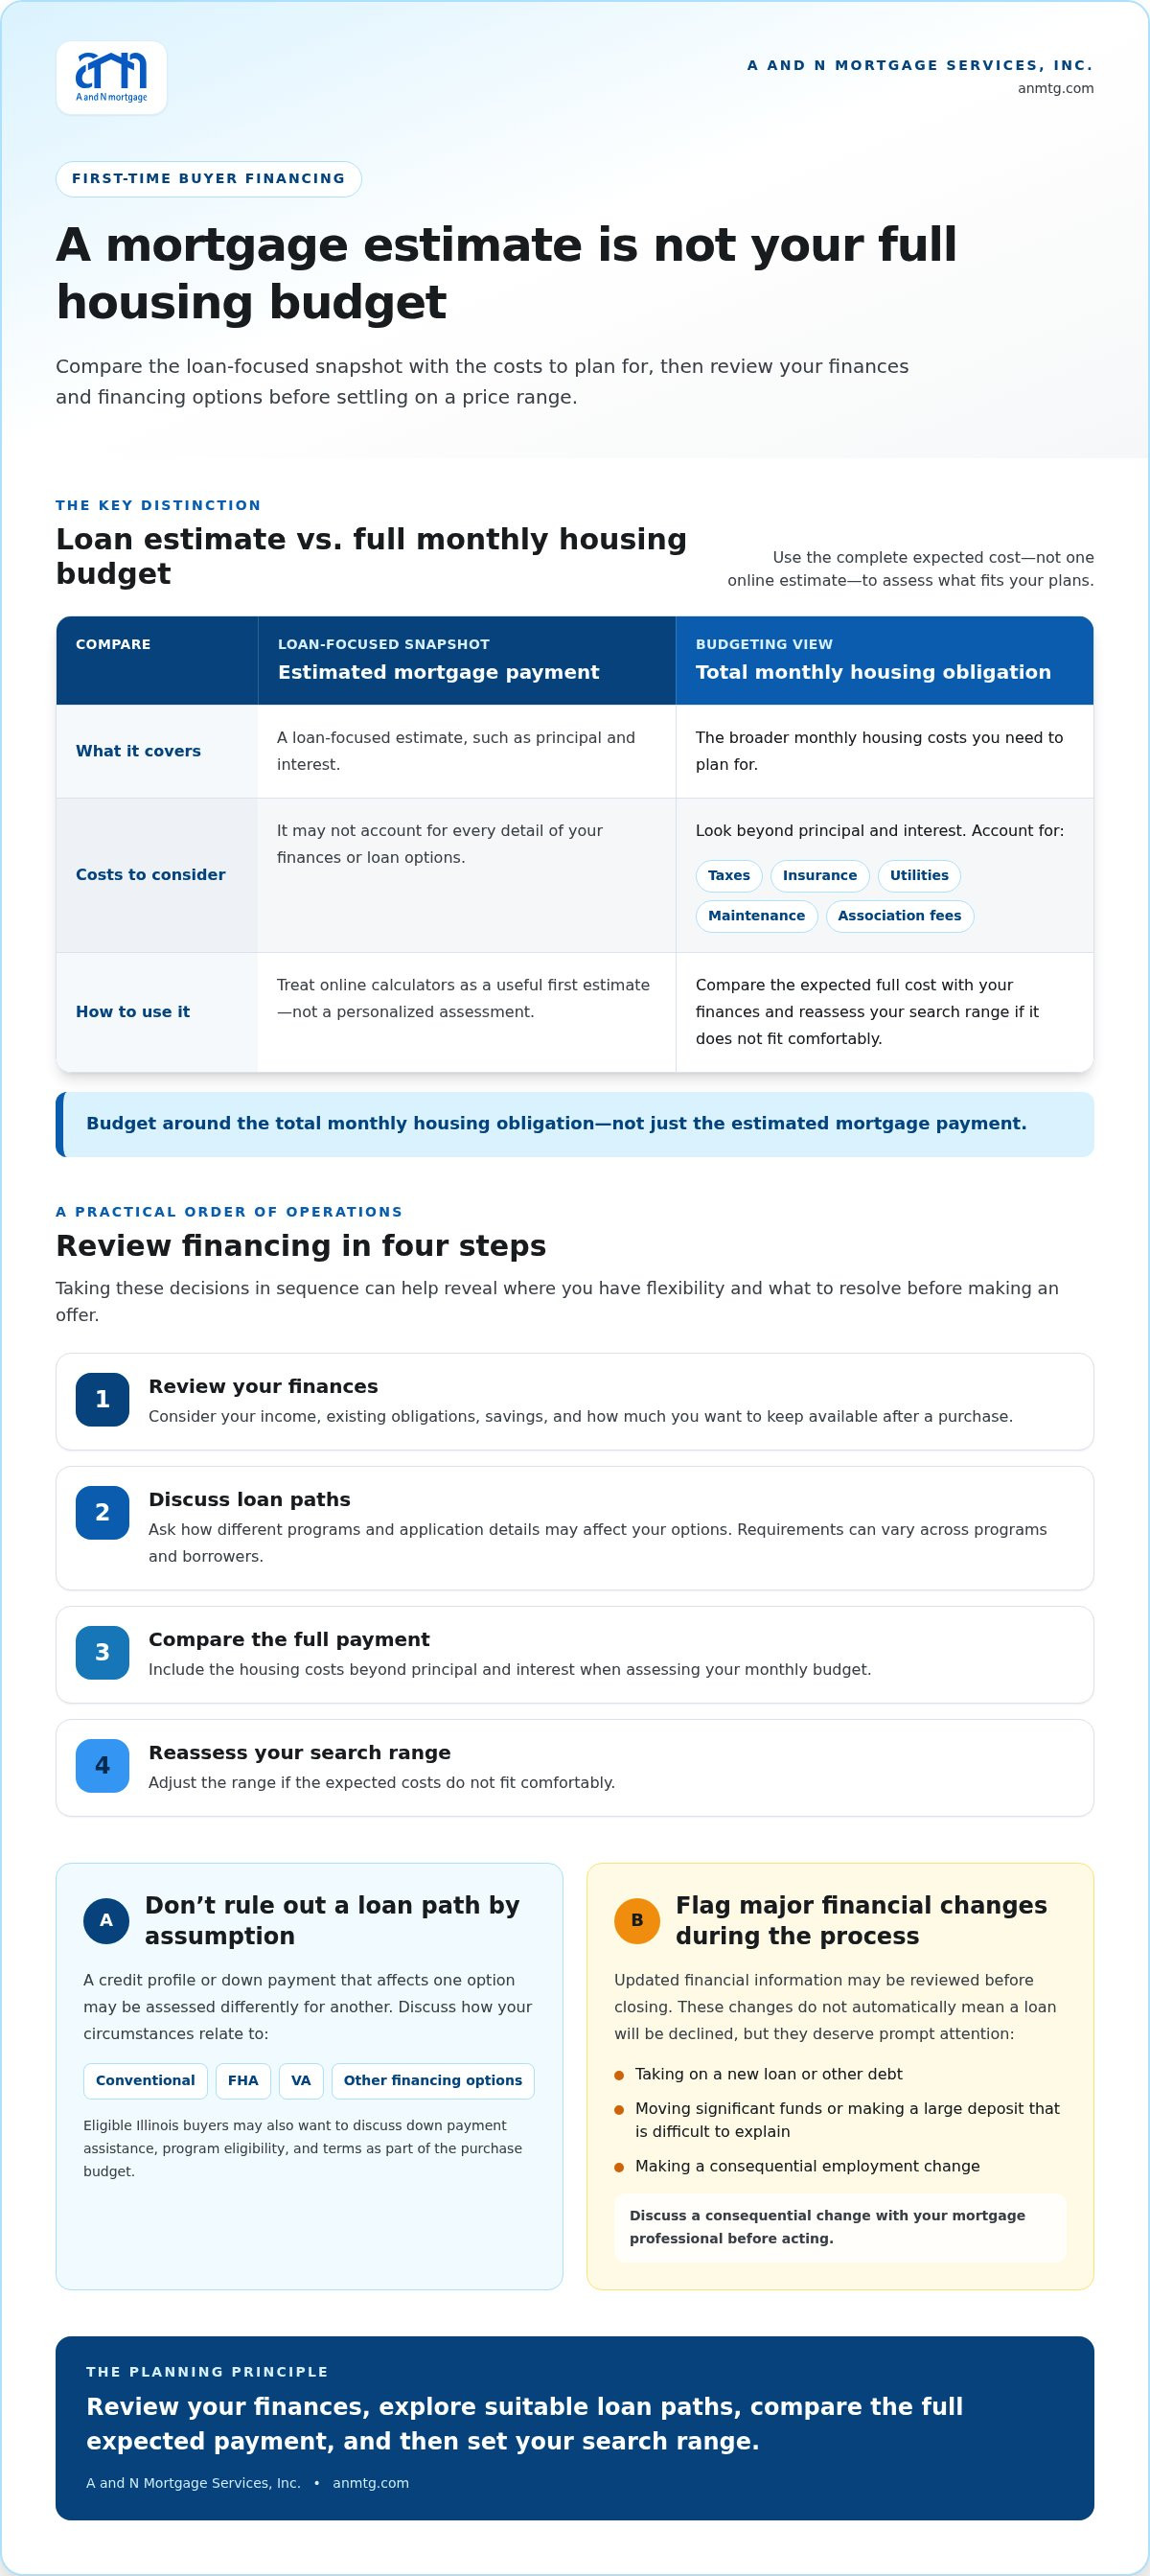
Financing decisions are easier to evaluate when you take them in sequence instead of relying on one online estimate or rule of thumb. Review your finances, discuss loan paths that may suit your circumstances, compare the full expected payment, then reassess your budget before settling on a price range. This process can show where you have flexibility and which questions to resolve before making an offer.
An estimated mortgage payment is a loan-focused snapshot. Your total monthly housing obligation is the amount to plan your budget around. The HUD home buying guide offers general information on affordability and loan shopping. Your own figures and circumstances call for a personalized review.
Loan requirements aren’t identical across programs, borrowers, or application details. A credit profile or down payment that affects one option may be assessed differently for another. Blanket online rules can lead buyers to dismiss a path that may be worth discussing. A mortgage professional can help you understand how your circumstances relate to conventional, FHA, VA, or other financing options. For more detail, see our 2026 guide to credit scores for a mortgage.
Down payment assistance may also be relevant for eligible Illinois buyers. Instead of building your plan around an assumed minimum or maximum, discuss how available programs and your finances could fit together. Consider program eligibility and terms as part of your overall purchase budget. Our overview of Illinois down payment assistance programs is a good starting point.
After you apply, don’t assume your finances are irrelevant to the purchase. A new loan, a large deposit that’s difficult to explain, or an employment change may prompt questions or affect how your application is assessed. Lenders may review updated financial information before closing, and the outcome can depend on your application details. These changes don’t automatically mean a loan will be declined, but they deserve prompt attention.
Before taking on debt, moving significant funds, or making a consequential job change, talk with your mortgage professional. Clear, timely information gives you a chance to understand how a decision could affect your financing before you act.
For Chicago buyers, a tailored conversation can connect your budget and goals with suitable financing paths. Explore personalized mortgage guidance as you turn initial estimates into a plan you can evaluate with greater confidence.
A home can look affordable based on its estimated mortgage payment and still stretch your budget once recurring costs are included. One of the first time home buyer mistakes to avoid is treating principal and interest as the full cost of owning a property. Ongoing costs shape what you’ll need to manage month after month, so affordability goes beyond principal and interest.
Use this comparison to identify what belongs in your estimate. Actual expenses depend on the property and your circumstances, so investigate each home rather than relying on a general figure.
A lender’s assessment of what you may qualify to borrow isn’t the same as a household budget that feels manageable. Before committing to a price, account for recurring costs you’ll carry alongside the loan payment. For Chicago-area homes, review the property’s tax information; our guide to Illinois property taxes for Chicago buyers explains what to look for. For a condo or a home in an association, include applicable fees, too. Two similarly priced properties can have very different monthly costs.
Upfront expenses also affect how much cash you’ll need to complete a purchase. Keep those one-time costs separate from the recurring expenses in your monthly comparison, so you can see both the cash needed to buy and the cost of owning the home. To set a number you can live with, read how much house you can comfortably afford.
A listing can’t tell you everything about a home’s condition or what it will be like to live there. Arrange an appropriate inspection and review the findings carefully. Use questions about the property’s condition to guide any follow-up before moving forward. An inspection is one important part of due diligence, not a substitute for deciding whether the home meets your priorities. Buying a condo? A full condo review can surface building-level issues early.
Look beyond the front door, too. Consider your commute, access to services, noise, and whether the neighborhood suits your routines. If possible, visit at different times of day to experience the surroundings beyond a single showing. Take notes, then compare each home against your priorities and full budget before deciding.
An accepted offer is a major milestone, but it doesn’t end the decision-making. Deadlines, inspection findings, lender requests, and final paperwork all need attention. A simple tracking system can keep each step visible and reduce the chance of overlooking a detail while you’re focused on the excitement of buying.
Use this checklist as a practical guide. Terms and timelines vary by transaction, so review the documents and your responsibilities before moving forward.
Pause before committing and compare the property with the priorities you set earlier. Does the expected payment still fit your budget? Are you comfortable with the home’s condition and any repairs you may need to consider? Offer terms, timelines, and available protections depend on the transaction. Don’t waive an important safeguard to make an offer more appealing without understanding the specific risks and terms. Make sure you understand deadlines and obligations before signing purchase documents.
Keep a copy of the offer and add key dates to a calendar as soon as they’re established. If a term is unclear, ask for an explanation before agreeing to it. Clarifying an obligation can help you make a more informed decision than relying on an assumption or rushing to meet a deadline.
Once the transaction is underway, use one secure, consistent system to track lender communications, requested documents, inspection information, and important dates. Mark deadlines clearly and keep copies of what you send. If a document or condition doesn’t make sense, ask a timely question rather than guessing. Coordinate mortgage updates with property-related decisions, especially if inspection findings prompt you to reconsider the home or its terms.
Organization won’t remove every complication, but it can help you spot unanswered questions while there’s still time to address them. These are practical first time home buyer mistakes to avoid: overlooking a deadline, signing without understanding a term, or leaving a property concern unexamined. A mortgage professional can help clarify financing-related requests as you work through the transaction.
Discuss your mortgage questions with A and N Mortgage Services, Inc.
You’ve considered decisions that can affect your budget, property choice, and purchase timeline. Now turn those points into a mortgage plan shaped around your circumstances instead of relying on a generic rule or estimate. Many first time home buyer mistakes to avoid become easier to recognize when you know what to ask and have a clear way to evaluate the answers.
Start with a short action plan:
You don’t need every detail settled before you start a conversation. Ask what documents and financial information can help clarify possible loan paths. Be ready to discuss your income, savings, approximate timeline, and comfort with ongoing housing costs. Sharing your priorities helps make the discussion relevant to your plans, whether you’re beginning to explore or preparing for a purchase.
Conventional, FHA, VA, jumbo, USDA, and other loan programs have different features and considerations. A mortgage professional can help explain which paths may be relevant to your circumstances. Loan guides like Best Mortgage for First-Time Buyers: Find the Right Fit can also help you explore individual programs in more detail, without treating one option as the right fit for every buyer.
Financing needs vary with income, savings, the property you’re considering, and what you want your monthly budget to accommodate. A buyer focused on a particular savings goal may weigh options differently from someone whose priority is keeping more funds available after closing. The useful question isn’t simply, “Which loan is best?” It’s, “Which options are worth considering for my goals and financial picture?”
A and N Mortgage Services, Inc. is a Chicago-based residential mortgage lender offering multiple loan programs and personalized guidance for home buyers. A tailored conversation can help you understand potential financing paths and identify questions to resolve as you move forward. It won’t replace property inspections or your own review of the home, but it can bring clarity to financing decisions.
When you’re ready, bring your questions and priorities to the conversation.
Explore mortgage guidance for your home-buying plans
Your first home purchase doesn’t have to be guided by guesswork. Keep your priorities visible as new details emerge, and give yourself time to understand the choices in front of you. Reviewing the first time home buyer mistakes to avoid isn’t about predicting every challenge. It’s about asking informed questions and making decisions that fit your circumstances.
As you move forward, write down the questions you still need answered and the decisions you’ve already made. That record can help you stay grounded when a property, deadline, or new financing information changes your perspective. You don’t need every answer today. One thoughtful next step is enough to build momentum.
With a plan that reflects your needs and a mortgage professional to guide the financing conversation, you can approach the next stage with greater confidence. Take it one decision at a time.
No, a 20% down payment isn’t a universal requirement. Some conventional loan programs may allow eligible first-time buyers to put down as little as 3%, while FHA loans may allow 3.5% for borrowers who meet applicable requirements. A smaller down payment can affect other parts of the financing, such as private mortgage insurance (PMI), so compare loan terms and total costs with a mortgage professional before deciding how much to put down.
Yes, an imperfect credit score doesn’t automatically rule out buying a home. Credit requirements differ by loan program and application: for example, 2026 guidance indicates that conventional loans typically require a score of at least 620, while FHA borrowers may qualify with lower scores under different down payment requirements. Lenders also consider other financial details. A personalized review can help you understand which options may be worth exploring.
A job change could affect how your mortgage application is assessed, so tell your mortgage professional promptly rather than waiting until closing. The impact may depend on factors such as the timing of the move, your new pay structure, and the documentation available. A change doesn’t automatically mean your purchase can’t proceed, but your lender may need updated information to reassess your application and next steps.
In most cases, an inspection is a valuable way to learn more about a home’s visible condition before proceeding. It can identify concerns that deserve clarification, further evaluation, or discussion as you consider the purchase. An inspection has limits and can’t guarantee that every issue will be found. If a finding raises questions, consider whether a qualified specialist should evaluate that specific concern before you decide.
It depends on what “accepted” means in your situation and the terms of the transaction. A verbal agreement, a signed purchase contract, and a contract that includes specific conditions may have different implications. The seller may also receive other offers while your purchase is underway. Review the signed documents and ask your real estate professional or attorney to explain how the contract addresses competing offers and your obligations.
Property taxes add to the cost of owning a home and can make two similarly priced properties differ in overall affordability. If taxes are included in an escrow payment, the amount collected monthly is based on an estimate and may be adjusted as tax information changes. For a Chicago-area home, review the specific property’s tax details and include them in your budget rather than relying on a neighborhood-wide assumption.
Yes, eligible buyers may find assistance through state, county, or Chicago-area programs. 2026 program information includes Chicago’s HomeGrown Purchase Assistance Grant, Cook County down payment assistance, and IHDAccess assistance. The programs described offer different forms and amounts of support, subject to eligibility and program terms. Review current application periods, funding, and requirements before building assistance into your purchase plan.
Welcome to a better mortgage experience! In just few minutes you can find out what you qualify for and explore multiple loan options and interest rates.
Complete our short and intuitive pre-approval interview to get started.